top of page

V12 Retail Finance Q3 Data Shows Home Improvement Finance More Than Doubling


New quarterly data from V12 Retail Finance shows that UK consumers continued to turn to point-of-sale finance for high-value purchases in the third quarter of 2026. Total finance values across the platform grew 7% between July and September compared with Q3 2025, and were almost 20% higher than in the same period of 2024.


The quarter got off to a challenging start as prolonged hot weather and a busy international sporting calendar disrupted normal shopping patterns in July. However, each month of the quarter was ahead of the same month in 2025, and demand strengthened as the summer went on. As in the first half of the year, growth came mainly from categories linked to the home, health and practical everyday purchases. This suggests that households remain willing to commit to significant spending, but continue to be selective about where they do so.


Andrew Phillips, Managing Director of V12 Retail Finance said:

"The third quarter shows a consumer who is still willing to spend on what matters most, even when the backdrop is far from straightforward. July was a difficult month for many retailers, but demand held up and strengthened through August and September."

"The standout trend is the continued investment households are making in their homes. Home improvement finance more than doubled year on year in the quarter, and that reflects a broader shift we have been tracking for some time, as people choose to improve the homes they already have rather than move."


"Consumers remain cautious about the wider economic picture, and we expect them to stay selective. But the strength and breadth of demand across our portfolio gives us confidence as retailers head into Black Friday and the Christmas trading period."


Home improvements emerge as the defining trend of 2026

Home Improvements was a standout performer in V12’s portfolio in Q3. Finance values rose by around 112% year on year, and the pace of growth increased each month. Values were up approximately 56% in July, 107% in August and 163% in September.


The category has now grown almost fourfold in quarterly value since Q3 2024, and now accounts for around 7% of total finance values, compared with less than 4% in the same period last year. Across the first nine months of 2026, home improvement finance values are up by around 73% year on year. This builds on the multi-year pattern of increased investment in property-related projects that V12's earlier data releases highlighted.


Furniture remains the anchor of demand

Furniture remained the largest category by a significant margin, accounting for close to 49% of all finance values in Q3 2026. Finance values held broadly stable, rising around 1.5% year on year on what had been a strong Q3 2025.


Performance varied through the quarter, with July softer as warm weather reduced footfall, particularly at retail park locations. August was a stronger month for the category, with finance values rising nearly 9% year on year as cooler temperatures and Bank Holiday promotional activity brought customers back to stores. On August Bank Holiday Monday alone, applications approved across V12's portfolio rose by almost 40% compared with the same day in 2025, with furniture retailers making a significant contribution.


Healthcare and practical categories continue to grow

Healthcare and dental finance values rose by around 6% year on year, and are up by more than a third compared with Q3 2024. The category accounted for around 12% of V12's total finance values in the quarter. This reflects continued consumer willingness to invest in dental and elective treatment, supported by the expansion of V12's healthcare provider network.


Growth was also strong across several practical and lifestyle categories. Consumer electrical finance values more than doubled year on year, rising by around 126%. Cycles grew by around 24%, with double-digit growth in every month of the quarter. Motor finance rose by close to 6%.


Signs of stabilisation in discretionary categories

In Q1, discretionary luxury categories were under pressure. In Q3, there were early signs that this pressure is beginning to ease. Jewellery, the second largest sector by value, returned to growth, with finance values rising nearly 3% year on year. This marks a positive step after a softening trend that had been evident since mid-2024.


Other discretionary categories remained more subdued. Art saw a decline of close to 8%, while music was broadly flat. This suggests that while sentiment around non-essential purchases may be improving, households are still exercising restraint in some areas.


Retailer network continues to expand

V12's retailer network continued to grow during the quarter. The most significant milestone was the launch of V12's partnership with Magnet, which went live across all 150 Magnet stores in July and made a strong early contribution to the growth in home improvement finance. The sector also benefited from continued growth among retailers introduced through broker partners.


"What has been particularly encouraging this quarter is how broad the growth has been," added Andrew Phillips.

"We have seen strength in our largest categories, in healthcare and in practical purchases, and early signs of recovery in jewellery. Combined with the momentum in home improvements and new partnerships such as Magnet, that gives us a solid platform as we move into the busiest trading period of the year."

Most Read

Hill Cross Furniture Raises £1,500 For Overgate Hospice

Hill Cross Furniture Raises £1,500 For Overgate Hospice

North Yorkshire furniture specialist Hill Cross Furniture has presented £1,500 to Overgate Hospice after taking on a 1,042-mile cycling challenge inspired by the team’s work on the hospice’s new Inpatient Unit.

High Street Gloom as Leicester City Centre Welcomes New Openings

High Street Gloom as Leicester City Centre Welcomes New Openings

Leicester continues to buck the national narrative of high street closures as a new wave of restaurants, cafés, fashion stores and independent businesses open their doors across the city centre.

V12 Retail Finance Q3 Data Shows Home Improvement Finance More Than Doubling

V12 Retail Finance Q3 Data Shows Home Improvement Finance More Than Doubling

New quarterly data from V12 Retail Finance shows that UK consumers continued to turn to point-of-sale finance for high-value purchases in the third quarter of 2026.

Categories

Oct 19, 2023
3 min read

Using artificial intelligence (AI) in our everyday lives, and in business, is firmly in the mainstream and it’s now commonly accepted that any organisation that doesn’t ultimately integrate AI into its services and offering is going to fall behind.


Research from Manx Financial Group asked brokers about advancements in AI, and how it will affect small and medium-sized enterprises (SMEs) over the next twelve months. 40% said it would be used to further facilitate commercial finance application decisions, while a fifth (20%) of SME brokers thought it would be used to identify new business opportunities. 19% thought SMEs would use it to determine future business risk and one in ten (9%) believe it will replace back office and non-client facing roles.


But how does an industry like alternative lending for SMEs – which requires sometimes emotive decision-making that requires a human thought process – adopt unemotive artificial intelligence?


Enhancing Customer Service

AI algorithms can be deployed to very quickly analyse vast amounts of data, including financial records, business performance, and wider industry trends. All this data is then used to provide the basis of highly personalised loan recommendations to founders, which ultimately increases the chances of loan approval and – in a world where personalisation is expected from customers – higher client satisfaction.


Streamlined Application Processes

Traditional loan application processes can be arduous, time-consuming and complex, leading to frustration for SME owners whose time is better spent on running their business. AI-powered alternative lending platforms can simplify and expedite the application process through automation. Chatbots and virtual assistants can guide applicants through the necessary steps, collect required information, and provide real-time support – saving on both time and paperwork.


24/7 Accessibility

AI has made chatbots increasingly intelligent and almost unrecognisable from the 'computer says no' chatbots of old. This allows customers to speak to their lenders 24/7, and while a chatbot still won’t replace an actual human being to speak to, it does mean that basic queries can be answered, and waiting times reduced.


There are also financial and security benefits to utilising AI – particularly when it comes to fraud and risk assessment of complex structures.


Real-time Fraud Detection

AI's ability to process and analyse data in real-time significantly strengthens fraud detection capabilities. By monitoring ongoing transactions and evaluating patterns, AI algorithms can swiftly identify suspicious activities and potential fraud attempts – for example, is the customer suddenly checking their account multiple time a day, or at strange times? This proactive approach allows lenders to mitigate risks promptly, protecting both parties’ financial losses.


AI can also enable secure authentication mechanisms such as facial recognition or voice biometrics, adding an additional layer of security.


Advanced Risk Assessment

As already mentioned, AI excels in analysing large volumes of data and identifying patterns that human analysts may overlook, and by leveraging machine learning algorithms alternative lending platforms can assess the creditworthiness of SMEs incredibly accurately. AI algorithms can analyse and take data points from credit histories, transaction records, social media activity, and other relevant data points to generate comprehensive risk profiles.


That said, this is the area where that human interaction is still needed – many lenders will ensure that a person takes a second opinion on more complicated applications – for example when historic financial or credit data also needs to be considered.


AI is the future, and its advent has brought significant advancements in alternative lending at a much-needed time for SMEs, allowing them to faster overcome financing challenges and fuel their growth.


AI, used correctly, will also give alternative lenders the advantage over traditional lenders, who can struggle to keep up with the rapidly changing digital world. It will also streamline resource within our organisations, allowing us all to spend our energy and personnel hours on tasks where human touch really is irreplaceable.

While there are common misconceptions that AI 'will take our jobs' it is our feeling that it is is used properly, it is a tool that will just make us better at them.
Most Read

Hill Cross Furniture Raises £1,500 For Overgate Hospice

Hill Cross Furniture Raises £1,500 For Overgate Hospice

North Yorkshire furniture specialist Hill Cross Furniture has presented £1,500 to Overgate Hospice after taking on a 1,042-mile cycling challenge inspired by the team’s work on the hospice’s new Inpatient Unit.

High Street Gloom as Leicester City Centre Welcomes New Openings

High Street Gloom as Leicester City Centre Welcomes New Openings

Leicester continues to buck the national narrative of high street closures as a new wave of restaurants, cafés, fashion stores and independent businesses open their doors across the city centre.

V12 Retail Finance Q3 Data Shows Home Improvement Finance More Than Doubling

V12 Retail Finance Q3 Data Shows Home Improvement Finance More Than Doubling

New quarterly data from V12 Retail Finance shows that UK consumers continued to turn to point-of-sale finance for high-value purchases in the third quarter of 2026.

Categories

An Artefact That Waves To The Past Is Discovered

An Artefact That Waves To The Past Is Discovered

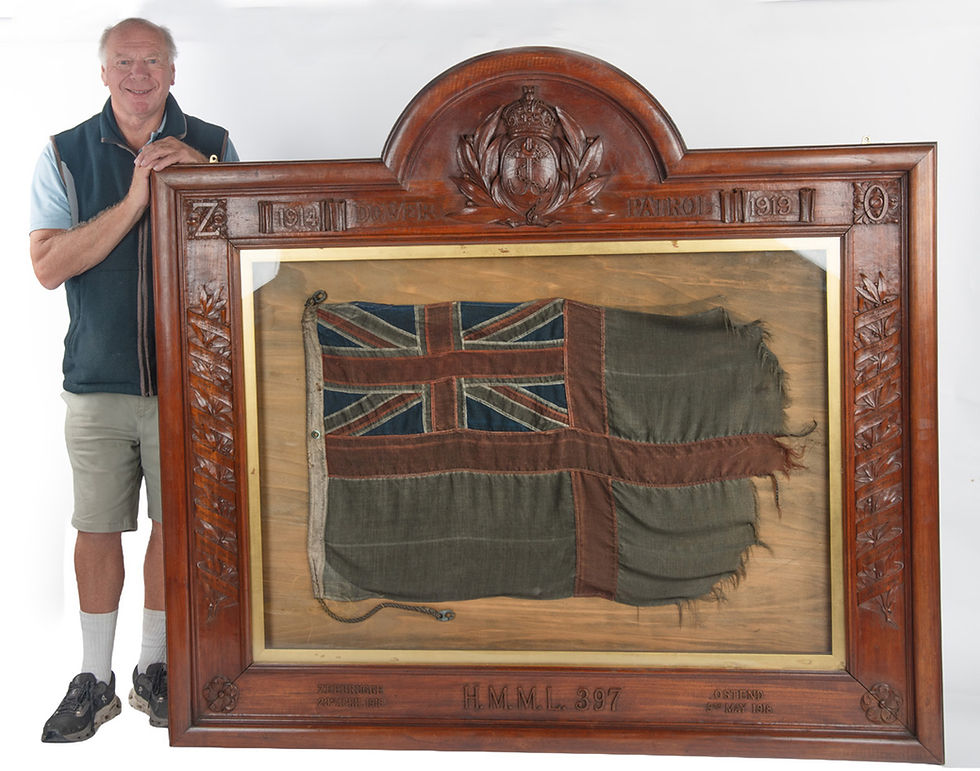
An astonishing relic from the legendary Zeebrugge and Ostend raids in World War I has emerged – shining a light on a forgotten act of heroism.

F1 Battery Component Maker Battles Global Giants For Pole Position

F1 Battery Component Maker Battles Global Giants For Pole Position

A family-owned business is taking on some of the world's biggest battery markets after transforming itself from a specialist distributor into an advanced manufacturer in just five years.

Business Rates Shake-Up Risks Creating Uncertainty For UK SMEs

Business Rates Shake-Up Risks Creating Uncertainty For UK SMEs

Small and medium-sized businesses face fresh uncertainty over how future business rates changes could affect their plans for growth, investment and recruitment.

Recent Posts

bottom of page